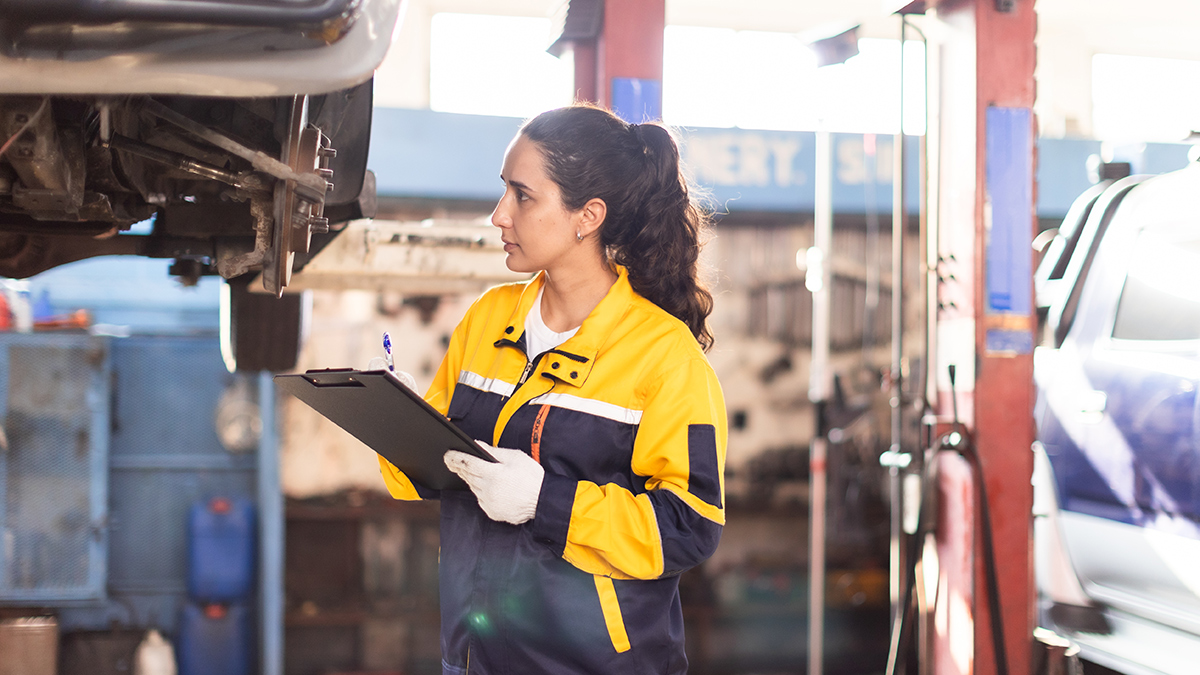
Your insurer usually chooses the repairer, and only some policies let you nominate your own
Insurers can fit aftermarket or second-hand parts rather than new genuine ones depending on the terms in your product disclosure statement (PDS)
For minor damage, paying out of pocket may cost less than your excess plus the premium rise
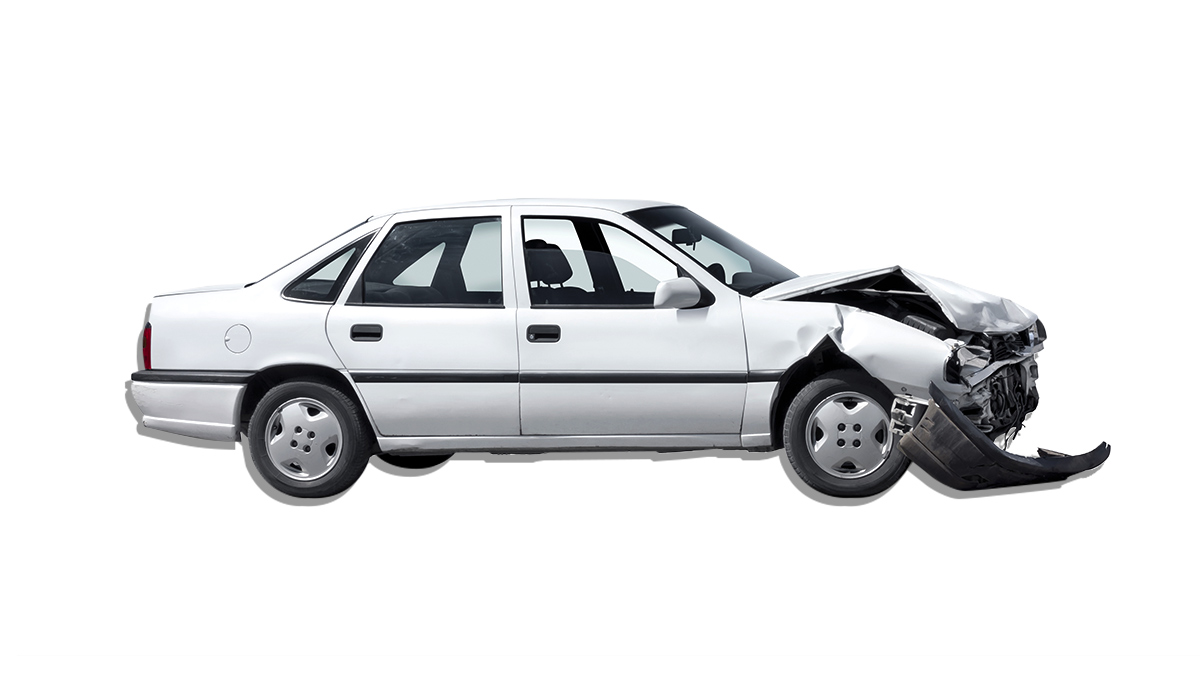
Comprehensive car insurance pays to fix your car if it’s damaged by fire, natural disaster, vandalism or an accident, even if you’re at fault. But it doesn’t promise your car will get fixed the way you expect.
Your insurer may decide who does the work, whether the parts are new or second-hand, and how long the repair is guaranteed.
To help you get back on the road as quick as possible, here’s our expert guide to everything you need to know (including those tricky PDS terms) and what to watch out for.
1. Your insurer might choose the repairer, not you
Many insurers have a network of repairers and will direct you to one of those to fix your vehicle. If you’d prefer to use a repairer of your choice, you need to look out for a policy that offers “choice of repairer”, or add it as an extra and pay a fee.
If the insurer chooses your repairer, you may have to travel some distance to drop off your car, get home without a car, and then back out there when it’s fixed.
But the upside is that this also means you don’t need to get too involved with the repair, and you can leave negotiations with the repairer up to the insurer. In addition, when using the insurer’s repairer you can be assured that the only out of pocket cost will be your excess.
If you’d prefer to use a repairer of your choice, you need to look out for a policy that offers “choice of repairer”
If you have the option to choose your own repairer, you can pick one in a convenient location, or one you’re familiar with. But sometimes this adds complications and extra cost, like if the insurer doesn’t agree with the price they charge.
2. Repair guarantees can end when your policy does
A repair guarantee means your insurer will pay to fix the work again if a repair they funded later fails; either because it wasn’t done properly or because a part was faulty.
Guaranteed while you (or your family) own the vehicle
Most commonly, insurers guarantee repairs only while you own the car, regardless of whether you have choice of repairer. About two thirds of the 70 policies in our comparison (updated August 2026) do this. This includes policies from Allianz, Budget Direct, Coles, Everyday and Youi.
However, Aldi, Bank of Australia, BOQ and RACQ go slightly further and cover the repair while the vehicle is owned by you or a family member. Under these policies the guarantee ends when you sell the car, so it isn’t something you can pass on to a buyer.
Guaranteed for the life of the vehicle
As of August 2026, roughly a third of the 70 policies in our car insurance comparison guarantee repairs for the life of the vehicle, meaning the guarantee stays with the car rather than with you.
AAMI, Bingle, GIO, NRMA and Suncorp all offer this. To find one, filter our comparison table, or open the PDS and search (Ctrl/Command+F) for “lifetime”.
Only guaranteed while they still insure you
Two insurers we review will only guarantee repairs while they still insure you. RAA guarantees repairs only while it continues to insure the vehicle, and only if the work was done at its nominated repairer.
That’s a problem if you switch insurers regularly to chase a better price and means that your guarantee ends when your policy does. For example, RACQ lets you choose your own repairer but will only guarantee the repair if it was carried out at RACQ’s repairer.
Your policy’s PDS sets out what kind of parts your insurer can use to repair your car, and the terminology varies enormously between insurers.
Almost all of it falls into four categories:
Category
Also called
New or used
What it means
Genuine / Original Equipment Manufacturer (OEM) parts
Genuine parts, genuine new parts, OEM parts
New
Made by the vehicle’s original manufacturer, or by the supplier that made the part for them. Essentially identical — the difference is the logo on the box. Some use OEM parts during the manufacturer’s warranty period, then non-OEM or refurbished parts
Aftermarket
Non-genuine parts, non-OEM parts
New
Brand new, but made by a third party. Possibly not quite the quality of the original manufacturer’s. Some insurers specify ADR-compliant* parts
Refurbished
Reconditioned, remanufactured, exchange parts
Used, restored
Cleaned, serviced or upgraded back to near-original condition and quality-checked. Dearer than second-hand, cheaper than new
Second-hand
Recycled parts, reusable parts
Used
Typically taken from a low-mileage de-registered vehicle. Likely in near original condition. May be genuine or aftermarket in origin eg “recycled OEM parts”
*Australian Design Rules (ADR) compliant. The ADR are the national vehicle safety and performance standards that apply to certain parts of vehicles and are enforced by the states to ensure registered vehicles are roadworthy.
Spare parts glossary
ADR: Australian Design Rules – the national vehicle safety and performance standards for new cars
Aftermarket: not made by the original car manufacturer, or someone they commissioned
Exchange: repaired to recreate original condition
Genuine: new, made by the vehicle’s original manufacturer
Non-genuine: made by someone else
OEM: new, made by the manufacturer that made the part for the original vehicle
Non-OEM: not made by the original car manufacturer, or someone they commissioned
Reconditioned: repaired to recreate original condition
Recycled: from low-mileage deregistered vehicles; in near new condition
Refurbished: repaired to recreate original condition
Remanufactured: repaired to recreate original condition
Repaired: repaired to recreate original condition
Reusable: from low-mileage deregistered vehicles; in near new condition
Second hand: from low-mileage deregistered vehicles; in near new condition
Used: from low-mileage deregistered vehicles; in near new condition
4. Claiming isn’t always worth it for small repairs
For small or cheaper repairs, it can be cheaper in the long run to pay for the repair yourself, rather than claiming on your car insurance.
This is because insurers use claims history to assess risk, meaning more claims result in higher premiums in the future. And most use overall claims, not just ones where you’re at fault.
For smaller bingles, it might be cheaper not to claim on your cover.
So if a repair is only going to cost a little more than your excess, it might be wise to pay for it out of your own pocket if you can. And it goes without saying that if the cost of repairing your car is less than your insurance excess, you’ll save money by not claiming on your car insurance.
5. You can choose your payout if your car is written-off
When taking out your policy, most insurers give you the option to be paid either an agreed value or market value if your car is deemed too expensive to repair.
Agreed value
This is when you specify a dollar figure (that your insurer deems reasonable) to be paid if your car is written off. It costs a bit extra to specify an agreed value, but gives you peace of mind that you will have enough to replace your car with something you’re happy with should it be written off, and if your car has depreciated your payout won’t be affected.
Market value
This fluctuates according to the price an average car like yours would sell for (if it wasn’t damaged) at the time that the insurer pays out. It’s not what you paid for your car, what it was worth when you took out the policy, or what it’s worth to you. It may be less than you expect. Most policies provide a market value payout by default.
6. You might not have to pay excess on windscreen claims
Almost one in five policies offer zero excess on glass repairs once a year as standard. This is because replacing damaged glass often costs less than your excess. Find these policies in our car insurance review or open the PDS and do a search (Ctrl/Command +F) for “windscreen” or “glass”.
Almost all of the rest offer zero or reduced excess on glass repairs as an additional feature for an extra fee. Some offer one repair with zero excess, and others offer optional excess reduction for repair.
Some insurers have limits on the number of repairs or replacements, and some will repair, but not replace.
Jane Bardell is a Content producer in the Insurance and utilities team. She writes about home, car, pet and health insurance.
Previously at CHOICE, she checked facts, figures and statistics as a Verifier with the Editorial and investigations team.
Jane has a Bachelor of Science from the University of New South Wales. LinkedIn
For more than 60 years, CHOICE has been fighting the good fight for Australian consumers.
In the past year alone we've uncovered systemic issues with sunscreens, investigated shonky supermarket pricing, fought for stronger scam protections and helped make complex energy pricing fairer and clearer.
CHOICE is here to provide unbiased advice and independent testing in our world-class labs. We buy the products we test, just like you do, and our expert reviews are influence free. We’re here to help you choose smarter. Hopefully you’ll also save some money along the way.
Thanks to CHOICE, you’ll never be alone when a business treats you unfairly. You can support our work by joining or donating to our cause.