You could end up being out of pocket with a cash settlement, as your insurer may only pay out what it would cost them to rebuild, not what it will cost you to rebuild
A cash settlement may not include all the costs, as once you settle your claim, any damage that hasn’t yet been discovered may no longer be covered
It’s very important not to sign anything before you’ve had time to consider the cash offer properly
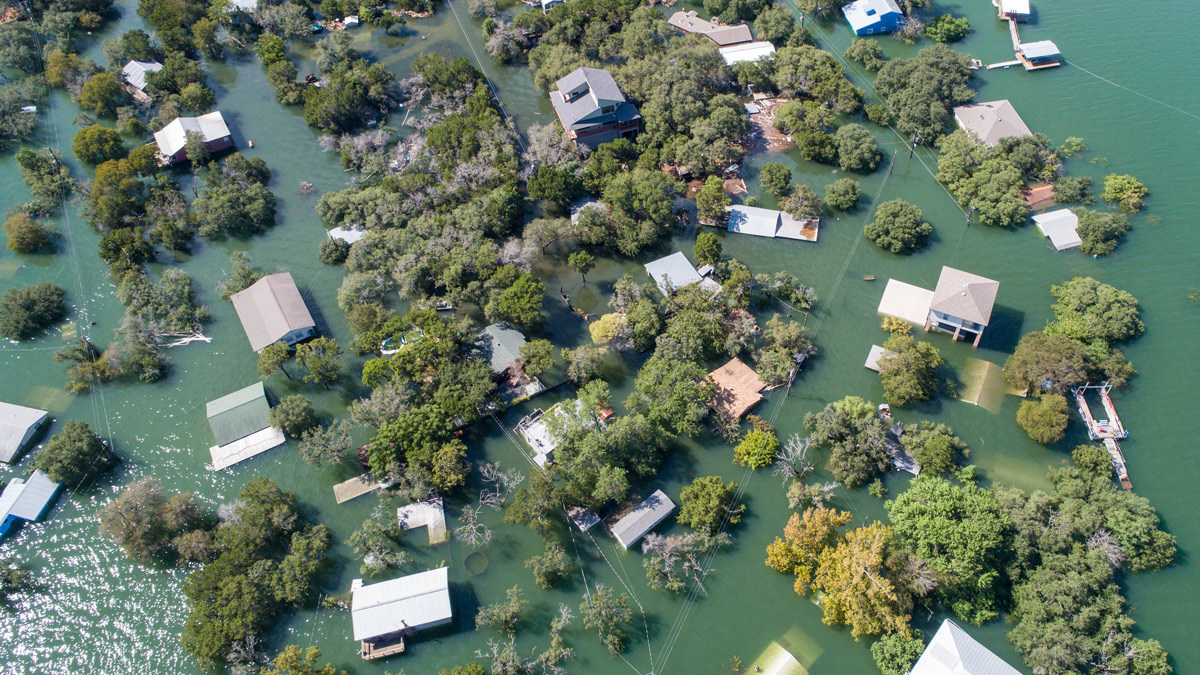
In 2023, Tropical Cyclone Jasper, the wettest tropical cyclone in Australian history, devastated Far North Queensland and resulted in over 10,000 insurance claims. An ASIC review of many of these claims, released in 2026, revealed the prevalence of insurers settling home and contents claims with cash payouts rather than managing repairs themselves, and also how risky these settlements can be for consumers.
Of the claims ASIC analysed, 63% were resolved with a full or partial cash settlement. Over half of the settlement offers were based on just one quote for repairing the damage, and over 70% of these single quotes were from one of the insurers’ preferred suppliers, which is likely to give that insurer a discounted rate (that won’t be available to the individuals paying for repairs with their cash settlement). Below, we highlight a number of traps to be aware of so that you don’t end up out of pocket.
It’s very important not to sign anything before you’ve had time to consider the cash offer properly. If the damage is significant, you may also want to get legal and financial advice.
How insurers settle home and contents insurance claims
If disaster strikes, you may need to make a claim. If your insurer covers your claim, there are usually three options for settlement. The insurer may agree to:
replace or repair your item
repair or rebuild your property, or
give you a cash settlement.
A cash settlement may be appealing if, for example:
jewellery you inherited from family members was stolen and no replacement could ever have the same sentimental value
you want to make renovations and improvements, like an open-plan living area, extra study or new deck, or
you don’t want to rebuild.
When will insurers offer a cash settlement?
Some instances of when an insurer may offer a cash settlement for your home include:
your council won’t allow you to repair or rebuild
some of the damage to your property isn’t covered (e.g. part of the damage to your roof was caused by a storm, but the roof was poorly maintained)
you were underinsured (e.g. new building standards will make it much more expensive to rebuild).
According to the Australian Financial Complaints Authority (AFCA), when an insurer offers a cash settlement instead of a repair or replacement, it must be “fair in the circumstances”, meaning that it should be sufficient to pay for the policy holder to arrange repairs.
They also need to provide you with a “Cash Settlement Fact Sheet”. This must show the settlement options and the total amount being offered with a breakdown of how the total was calculated, and it must inform you that you can request a review of the offer, and advise you to consider getting independent advice. It must also be titled, dated, in writing, and easy to understand.
If you’re considering a cash settlement, be careful – you could end up being out of pocket, as many will only pay what it will cost the insurer to rebuild, not what it will cost you to rebuild.
Insurers have deals with builders, industry knowledge and bargaining power, so they may get a better price than you’d get. If you choose to cash settle, you’ll also lose the benefit of the insurer’s guarantee for the repairs.
You should always obtain a number of quotes to make sure the cash settlement is fair and reasonable, and will be enough to complete all the repairs. If your damage occurred because of a major natural disaster in your area, bear in mind that there may be delays, and costs are likely to go up.
/info
Text-only accessible version
If you ask for a cash settlement, will your insurer pay out full retail costs? The following insurers will pay full retail costs if you request a cash settlement for building claims: AANT AHM Aldi Allianz ANZ Australian Military Bank Australian Seniors Bank Australia Bank First Bank of Melbourne Bank of us BankSA BCU Bank Bendigo Bank BOQ Bupa CBA Coastline Bank COTA Defence Bank Everyday Insurance Great Southern Bank Guild HCF Honey Horizon Bank Huddle Hume Bank Kogan MOVE Bank MyState Bank NAB National Seniors NRMA Over Fifty P&N Bank People First Bank QBANK QBE Queensland Country Bank RACQ RACV Real Insurance St.George Summerland Bank Sure The Capricornian The Mutual Bank TIO Westpac Youi.
The following insurers will pay full retail costs if you request a cash settlement for contents claims: AANT Aldi Australian Military Bank Bank First Bank of us BCU Bank Bendigo Bank BOQ CBA Coastline Bank Defence Bank Guild Honey Horizon Bank MOVE Bank MyState Bank NRMA P&N Bank People First Bank QBANK QBE Queensland Country Bank RACQ RACV Summerland Bank Sure The Capricornian The Mutual Bank Youi.
2. The cash settlement may not include all the costs
Once you settle your claim, any damage that hasn’t yet been discovered may no longer be covered. Get the damage properly assessed by a builder and make sure the insurer has added some contingency costs. The cash settlement should include any cover you have for extra costs, such as:
debris removal
demolition
professional fees (like those of an architect)
new building standards
storage for your contents
temporary accommodation.
Some insurance policies include cover on top of the sum insured for these costs.
3. Your bank may want your cash
If you’ve got a mortgage on your home, check with your lender what happens in the event of a cash settlement. Your lender may want repayment of part of the loan, or the cash settlement may even go directly to them. You may also be required to get approval for any works you undertake.
4. Your home may not be insurable until it’s repaired
Once you’ve accepted a cash settlement, your insurance policy is no longer valid and another insurer may not be prepared to insure a damaged property. Try to negotiate with your insurer to get cover until your home is repaired.
5. You’ll be your own project manager
Do you have the skills (and inclination) to be an owner-builder? If not, how much will it cost to engage an appropriate person, and are those costs accounted for in the settlement?
If you think a cash settlement offer is too low, try to negotiate with your insurer. You have the right to ask the insurance company for all the documents and information relating to your claim, such as expert reports they used to calculate the settlement amount. If you can’t come to a satisfactory agreement, make a complaint.
Contact the insurer’s internal dispute resolution team. If your complaint is not resolved, contact the AFCA Other places to get help include:
Jane Bardell is a Content producer in the Insurance and utilities team. She writes about home, car, pet and health insurance.
Previously at CHOICE, she checked facts, figures and statistics as a Verifier with the Editorial and investigations team.
Jane has a Bachelor of Science from the University of New South Wales. LinkedIn
Jane Bardell is a Content producer in the Insurance and utilities team. She writes about home, car, pet and health insurance.
Previously at CHOICE, she checked facts, figures and statistics as a Verifier with the Editorial and investigations team.
Jane has a Bachelor of Science from the University of New South Wales. LinkedIn
For more than 60 years, CHOICE has been fighting the good fight for Australian consumers.
In the past year alone we've uncovered systemic issues with sunscreens, investigated shonky supermarket pricing, fought for stronger scam protections and helped make complex energy pricing fairer and clearer.
CHOICE is here to provide unbiased advice and independent testing in our world-class labs. We buy the products we test, just like you do, and our expert reviews are influence free. We’re here to help you choose smarter. Hopefully you’ll also save some money along the way.
Thanks to CHOICE, you’ll never be alone when a business treats you unfairly. You can support our work by joining or donating to our cause.